

Budget Calendar
MiShell Software Systems
- 4.8
- 189.00 Reviews
- 10.00K
- Downloads
- $4.95
- Price
Screenshots
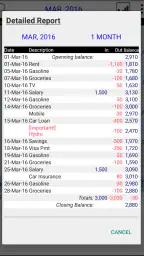
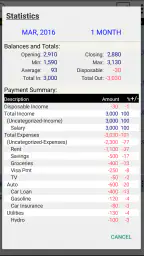
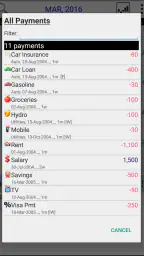
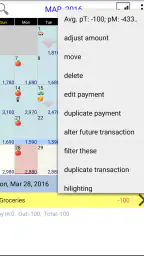
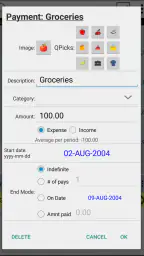
Budget Calendar Pros and Cons
Pros
- Clear calendar view makes upcoming bills and income easy to track.
- Recurring transactions reduce the need to enter regular expenses repeatedly.
- Budget categories help identify spending patterns at a glance.
- Useful reminders can help prevent missed payments and overdrafts.
- Simple interface is approachable for users new to budgeting apps.
Cons
- Advanced planning features may require time to configure properly.
- Manual transaction entry can become tedious for frequent daily purchases.
- Limited sharing options may not suit couples managing a joint budget.
- Too many categories can make the calendar feel cluttered.
- Some features may vary between Android and iOS versions.
 Analysis by All-app
Budget Calendar is a finance app from MiShell Software Systems that takes a refreshingly practical approach to managing money: instead of treating a budget as a list of categories, it lets me think about when money arrives and when expenses are due. That calendar-based view is the reason I find it interesting. It turns budgeting into a question I actually ask in daily life: “Will my balance cover everything between now and the next payday?”
I reviewed it as an Android budgeting tool, and my overall impression is that it suits people who plan around paydays, bills, subscriptions, and irregular expenses. Its store summary describes easy budgeting planning on a calendar, but the useful part is the change in perspective. A conventional expense tracker tells me where money went. This app is more concerned with how my available money may move through the month.
The application costs $4.95, carries an Everyone age rating, and has a 4.8 average from around 481 ratings, with roughly 189 written reviews. It has passed 10K+ installs, which suggests a focused audience rather than the scale of a mainstream banking app. The current version is 1.69, and it runs on Android 7.0 or later. Those details matter because this is a paid, deliberately focused tool, not a free all-in-one financial service.
Why the calendar view changes budgeting
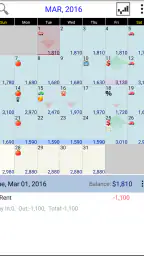
The central capability is simple to explain but more useful than it first sounds. I can place expected income and planned spending along a timeline, then judge the space between them. That makes the app especially relevant when the monthly total looks acceptable but the timing is uncomfortable.
For example, imagine that rent, utilities, transport, and a subscription all fall early in the month, while the next paycheck arrives later. A category-based budget may show that the total expenses are affordable. A calendar view exposes the cash-flow squeeze. That distinction is the strongest reason to choose this app over a basic notes file or a spreadsheet.
I also like that this approach encourages planning before spending. Instead of recording a purchase only after it happens, I can use the calendar as a forward-looking map. The result is less about judging yesterday’s coffee and more about seeing whether tomorrow’s obligations have room in the plan.
The important benefit is timing, not decoration. A calendar is valuable here because financial stress often comes from mismatched dates rather than from a completely unrealistic monthly budget. If a user regularly reaches the end of a pay period with too little available cash, this way of organizing information can make the problem visible earlier.
More Reads From Our News Desk

Switching to the Xbox App: What Changes in Your Gaming Routine

Coloring & Learn Review: A Satisfying Canvas, Cluttered Menus

Microsoft 365 Copilot on Your Phone: Who Actually Needs It?

Mafia City: The Crime Saga That Outshines Its Rivals

Woodturning Transformed: How OS Updates Enhance Your Craft

How Tiles Hop EDM Rush Redefines Music Gaming
What using it feels like day to day
In practice, I would begin by entering the income I expect and then adding the expenses that matter to the plan. The useful habit is to include predictable commitments first, before filling the calendar with flexible spending. That gives the timeline a reliable foundation. Once the fixed obligations are visible, I can decide how much room remains for groceries, outings, or purchases that can wait.
The calendar format also makes irregular costs easier to take seriously. Annual renewals, school-related spending, travel, repairs, and seasonal bills can be mentally invisible when I only think in monthly categories. Placing them on the date they are likely to matter encourages me to prepare for them instead of being surprised when they arrive.
I would not use the app as a replacement for checking my bank account. A plan is still a plan, and the balance shown by a financial institution remains the final authority. The app is most useful as a planning layer: I decide what should happen, compare that plan with reality, and adjust when an amount or date changes.
That distinction answers an important practical question: is this a banking app? No. It is better understood as a budgeting calendar. Someone looking for bank transfers, account aggregation, investment tools, or payment services should choose a different kind of finance product. Someone who wants a clear personal schedule for income and expenses may find the narrower focus more comfortable.
A realistic payday routine
Consider a person paid every two weeks whose major bills are monthly. On payday, the temptation is to treat the new balance as spending money. A calendar plan creates a useful pause. I can look ahead to the next rent date, upcoming utility payment, transport costs, and any recurring commitment before deciding what is genuinely available.
That routine is more helpful than checking a category total once a month because it connects each decision to a date. If I want to buy something today, I can ask whether it interferes with the obligations already placed later in the timeline. The app does not need to make that decision for me; its value is putting the relevant commitments in front of me at the right moment.
A second useful routine is a weekly review. I would compare completed spending with the plan, move or revise anything that changed, and look at the next stretch of the calendar. This is where the app can become more than a setup exercise. A budget that is never revisited quickly becomes a historical record, while a calendar that I maintain can remain useful for upcoming decisions.
For couples or families, the same method can help with conversations about timing. Even if only one person maintains the plan, a dated view is easier to discuss than a vague statement such as “we should spend less.” It can show that the problem is not necessarily total spending but several commitments landing close together.
Small planning techniques that make it stronger
One technique I would recommend is separating obligations from choices in the way I think about the calendar. Fixed bills should establish the minimum amount that must be protected. Flexible spending can then be considered around that boundary. This prevents an attractive discretionary plan from quietly consuming money needed for a non-negotiable payment.
Another is to enter uncertain income conservatively. If a payment date or amount is not dependable, I would avoid treating it as fully available until it is reasonably certain. The calendar is only as realistic as the assumptions behind it. Overly optimistic entries can make the future look safer than it is.
A third is to use the timeline to prepare for clusters of expenses. A single bill may be manageable, but three moderate costs arriving within a few days can create the real difficulty. Looking at the dates together helps me decide whether to reserve money earlier, delay a flexible purchase, or spread preparation across several pay periods.
These are not flashy features; they are better budgeting habits made easier by the app’s structure. That is also why I would not judge it by the number of extras it offers. Its success depends on whether the calendar helps me make better choices before money leaves my account.
Where the focused design can frustrate
The same narrow focus that makes Budget Calendar approachable may disappoint users who want a complete financial dashboard. If I expect automatic bank synchronization, detailed investment tracking, extensive reporting, or a large ecosystem of financial services, this is probably not the right purchase. A spreadsheet or a broader money-management platform may offer more flexibility and deeper analysis.
Manual planning also requires discipline. A calendar cannot know that a bill changed, that a purchase was delayed, or that an unexpected expense appeared unless I update the plan. Some people will appreciate that direct control; others will see it as extra work compared with an automatically connected service.
There is also a conceptual trade-off between simplicity and precision. A calendar can make timing immediately understandable, but it may not answer every accounting question. Users who need highly detailed category analysis, complex shared finances, or formal records for business use may outgrow it. I would keep those expectations in check before paying for the app.
The paid price is another consideration. At $4.95, the decision is not difficult for someone who specifically wants this style of planning, but a casual user might prefer starting with a notes app or spreadsheet. The advantage here is not that it eliminates budgeting effort. The advantage is that it gives that effort a structure designed around dates.
Who benefits most from the calendar approach
I think the strongest audience is anyone whose financial difficulty is caused by uneven timing. That includes people paid on a schedule that does not line up neatly with bills, households managing several recurring commitments, and users who understand their income but lose track of when expenses arrive.
It can also suit someone who finds traditional budgeting categories discouraging. A category limit may feel abstract, while a dated obligation feels concrete. Seeing the next payment on a calendar can make the consequences of a purchase easier to understand without turning the process into a judgment about every small expense.
People with irregular costs may gain more than users whose finances are extremely predictable. A calendar gives those occasional payments a visible place in the plan. It can encourage earlier preparation, which is often more realistic than trying to absorb a large cost in the month it finally appears.
I would be more cautious recommending it to a person who wants effortless automation. If the main goal is to connect accounts and have transactions categorized without regular input, a different finance app will likely be a better match. I would also steer business owners toward a dedicated accounting solution, because a personal budgeting calendar is not a substitute for business records.
How it compares with familiar alternatives
A spreadsheet gives more freedom than Budget Calendar. I can create custom formulas, elaborate categories, and long-term projections, but I also have to design the system and maintain it. For someone who enjoys building financial models, the spreadsheet may win. For someone who wants to open a purpose-built budgeting tool and focus on dates, this app is more direct.
A notes app is faster for jotting down bills, but it usually lacks the sense of an organized financial timeline. Notes can become a list that I forget to interpret. The calendar approach encourages me to look at the relationship between entries rather than merely storing reminders.
Traditional expense trackers are often strongest after spending has happened. They help answer where money went and may provide category summaries. Budget Calendar is more compelling before spending happens. Its distinctive question is whether the planned sequence of income and expenses remains workable.
Full-featured personal finance services may provide more automation and reports, but they can also introduce a heavier interface and more information than some users need. This app makes sense when I value a focused planning view and am willing to enter or maintain the details myself.
My recommendation after weighing the trade-offs
Budget Calendar is not a universal answer to money management, and I would not recommend it simply because it has a strong 4.8 average or a growing group of users. I recommend it for a specific reason: it makes cash-flow timing the center of the budgeting process. That is a meaningful distinction, especially for people who are technically within their monthly means but repeatedly struggle between paydays.
The developer, MiShell Software Systems, has kept the product positioned as a focused finance app rather than an overloaded financial suite. The current version, 1.69, remains compatible with Android 7.0 and later, so it can be considered by users on older supported devices as well as newer phones. Its Everyone rating also makes it broadly suitable from an age-classification standpoint.
Before buying, I would ask myself one question: do I need a forward-looking calendar for income and expenses, or do I really want automatic account tracking? If the answer is the first, the $4.95 price is reasonable for a tool built around that workflow. If the answer is the second, I would spend the money elsewhere.
My final view is positive but deliberately specific. Budget Calendar works best as a planning companion for real-life cash flow. It can help me see crowded weeks, protect upcoming commitments, and make spending decisions with dates in mind. It will not remove the need for honest estimates or regular updates, and it is not designed to replace banking or accounting software. For the right user, though, its calendar-centered method is clearer and more actionable than a simple list of categories.
Frequently Asked Questions
What is Budget Calendar and what can I use it for?
Budget Calendar is a personal finance app designed to help you visualize income, bills, recurring payments, and everyday expenses on a calendar. Instead of only showing totals in lists or charts, it lets you see when money is expected to arrive and when payments are due. This can make it easier to plan ahead, avoid missed bills, and understand your cash flow throughout the month.
Does Budget Calendar connect directly to my bank account?
The available features may depend on the version of Budget Calendar and your device or region. In general, the app is intended for manually organizing financial information, so you should check its current listing and privacy details before downloading. If bank synchronization is offered, review which institutions are supported and what permissions are requested. Manual entry may be preferable for users who want greater control over their financial data.
Can I track recurring bills, subscriptions, and future income?
Yes, Budget Calendar is particularly useful for recording repeating financial events such as rent, utilities, subscriptions, loan payments, salary, or other regular income. Once these entries are configured, you can review upcoming obligations on the calendar and estimate your available balance. It is still important to verify dates and amounts regularly, especially when bills change or payments are made outside the app.
Is Budget Calendar suitable for managing a household or shared budget?
Budget Calendar can be useful for individuals, couples, and families who want a clearer overview of shared expenses. You can organize household bills, planned purchases, and income in one calendar-based system. However, before relying on it for collaborative budgeting, check whether your version supports account sharing, synchronization, or multiple users. Without those features, everyone may need to update the same information manually.
Is Budget Calendar free, and are there in-app purchases?
Budget Calendar may offer a free download with optional premium features, depending on the platform and current release. Potential paid features can include removing advertisements, unlocking additional planning tools, accessing more customization, or enabling advanced reports. Pricing and subscription terms can change, so review the official Google Play or App Store listing before installing. Also check whether a trial automatically converts into a paid subscription.


